Imported Wood Pellets: Global Trade, Quality Standards & Supply Chain Guide (Importpellet) 2025
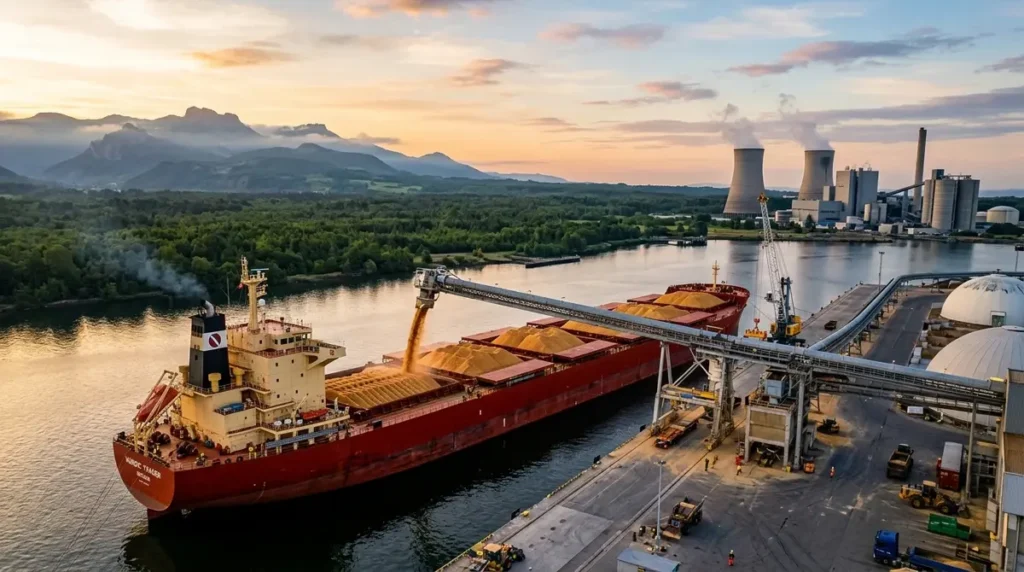
TL;DR: Imported wood pellets (Importpellet) are compressed biomass fuels shipped internationally for power generation and heating. Global production hit ~46 million metric tons in 2023. This guide covers the full supply chain, grading standards (ENplus A1, PFI, ISO 17225-2), CIF/FOB pricing benchmarks, RED III compliance, and the sustainability debate reshaping the $12 billion market.
You’re staring at a contract for 20,000 metric tons of biomass fuel. The supplier is in Georgia. Your power plant is in Rotterdam. Between those two points sits a sprawling global trade that most people never think about — until they absolutely need to understand it.
Imported wood pellets have quietly become one of the fastest-growing segments in renewable energy. In 2023 alone, global production reached roughly 46 million metric tons, with Europe and East Asia driving most of the cross-border demand. Whether you’re a procurement manager evaluating CIF quotes or a homeowner comparing stove fuel options, this guide breaks down everything that actually matters.
Table of Contents
- Quick Overview
- What Are Imported Wood Pellets? (Definition & Composition)
- How the Wood Pellet Supply Chain Works: From Mill to Port
- Why Europe and Asia Dominate Pellet Import Demand
- Wood Pellet Quality Standards: ENplus A1 vs. PFI vs. ISO 17225-2
- Pricing Benchmarks: CIF, FOB & Market Dynamics (2024–2025)
- Sustainability & RED III: The Environmental Debate
- Global Market Trends & Future Outlook (2025–2030)
- Key Takeaways
- FAQ
Quick Overview
- Global wood pellet production reached ~46 million metric tons in 2023 (Bioenergy Europe).
- The U.S. exported approximately 8.8 million metric tons, primarily from Southeast ports to Europe.
- ENplus A1, PFI Premium, and ISO 17225-2 are the three dominant quality grading standards.
- Industrial pellet CIF prices in Europe averaged €150–200 per metric ton through 2024.
- The EU’s RED III directive (adopted 2023) is tightening sustainability requirements for biomass imports.
- Major trade routes connect U.S. Gulf Coast ports to Rotterdam, UK terminals, and East Asian hubs.
What Are Imported Wood Pellets? (Definition & Composition)
Imported wood pellets are compressed biomass fuels — typically manufactured from sawdust and forestry byproducts — that are exported internationally for industrial power generation and residential heating. Unlike domestic fuel, imported wood pellets must comply with strict international trade standards, including ENplus A1, ISO 17225-2, and Sustainable Biomass Program (SBP) certifications to ensure low moisture content (below 10%) and minimal ash residue.
The production process itself is surprisingly straightforward. Raw wood waste enters a hammer mill, gets dried to below 12% moisture in a rotary drum, and is forced through a steel die under extreme pressure. The heat activates natural lignin in the wood, binding everything together without synthetic adhesives.
What separates a domestic pellet from an imported one isn’t the manufacturing process — it’s the logistics and compliance layer. Cross-border shipments must meet the importing country’s quality certifications, phytosanitary regulations, and increasingly, sustainability criteria tied to renewable energy subsidies.
According to the U.S. Energy Information Administration’s overview of biomass energy, biomass fuels are classified as renewable because the carbon released during combustion can theoretically be reabsorbed by regrowing forests. That classification, however, comes with significant caveats that we’ll unpack in the sustainability section below.
How the (Importpellet) Wood Pellet Supply Chain Works: From Mill to Port
If you’re sourcing industrial biomass pellets at scale, understanding the supply chain isn’t optional — it’s how you avoid costly delays and quality disputes at the discharge port.
Raw material sourcing. Most pellet mills sit within 50–100 miles of sawmills or timber processing facilities. They rely on residues — bark, shavings, offcuts — that lumber operations can’t sell as dimensional timber. Some larger producers also harvest low-grade roundwood, which is where sustainability concerns typically begin.
Production and quality control. After drying and grinding, the material is pelletized, cooled, and screened. Reputable mills run continuous moisture and durability tests throughout each shift. A batch that exceeds 10% moisture or fails the mechanical durability index won’t survive a six-week ocean voyage without degrading into sawdust.
Inland transport to port. Pellets move by rail or truck to coastal export terminals. In the U.S. Southeast, the Port of Savannah and the Port of Mobile handle the bulk of Atlantic-bound shipments. In Canada, Prince Rupert serves as the primary Pacific gateway.
Ocean freight. Bulk carriers load 30,000–50,000 metric tons per vessel. Transit times run roughly 10–14 days across the Atlantic and 25–35 days to East Asian ports. Freight rates directly impact your landed cost — a $15/ton swing in shipping can erase your margin overnight.
Receiving and storage. At the destination port — Rotterdam being Europe’s largest biomass import hub — pellets are unloaded into climate-controlled silos. Moisture exposure during discharge is the single biggest cause of quality degradation and contract rejection claims.
Why Europe and Asia Dominate Pellet Import Demand
The demand side of this market is heavily concentrated, and the reasons are almost entirely regulatory.
The European Union’s Renewable Energy Directive created massive financial incentives for utilities to convert coal-fired plants to biomass. The UK’s Drax Power Station alone consumes roughly 7 million tonnes of wood pellets annually — more than some entire countries produce. Since domestic European forests can’t supply that volume sustainably, imports fill the gap.
Japan and South Korea followed a similar playbook. Japan’s feed-in tariff program, launched after the Fukushima nuclear shutdown in 2011, guarantees premium prices for renewable electricity, including biomass co-firing. South Korea’s Renewable Portfolio Standard mandates that large utilities source a growing share of power from renewables. Neither country has the forest base to produce enough fuel domestically.
The result is a trade flow that runs predominantly from North America and Southeast Asia westward to Europe and eastward to Japan and Korea. Vietnam has emerged as a fast-growing supplier to East Asian buyers, while the U.S. Southeast remains the dominant source for European offtake contracts.
Wood Pellet Quality Standards: ENplus A1 vs. PFI vs. ISO 17225-2
If you’re negotiating a pellet supply contract, the grading standard referenced in that agreement will determine everything from your unit price to your acceptable rejection rates. Here’s how the three major systems stack up:
| Parameter | ENplus A1 (Europe) | PFI Premium (N. America) | ISO 17225-2 (International) |
| Ash content | ≤ 0.7% | ≤ 1.0% | ≤ 0.7% (Class A1) |
| Moisture | ≤ 10% | ≤ 8% | ≤ 10% |
| Calorific value | ≥ 16.5 MJ/kg | ≥ 16.9 MJ/kg | ≥ 16.5 MJ/kg |
| Mechanical durability | ≥ 97.5% | ≥ 96.5% | ≥ 97.5% |
| Diameter | 6 ± 1 mm | 6–8 mm | 6 ± 1 mm |
| Primary use case | Residential & commercial | Residential | Industrial & utility-scale |
| Governing body | European Pellet Council | Pellet Fuels Institute | ISO national member bodies |
ENplus A1 is the gold standard for European residential heating. If you’re selling bagged product to distributors in Germany, Austria, or Italy, this is the certification your buyers will demand before signing anything.
PFI Premium dominates the North American retail market. It’s slightly more lenient on ash but stricter on moisture, reflecting the different storage conditions pellets face in U.S. and Canadian warehouses.
ISO 17225-2 is the reference standard for large-scale industrial contracts. When a European utility issues a tender for 100,000 metric tons of biomass, the specification sheet will almost always cite ISO parameters alongside SBP sustainability requirements.
One practical tip from the field: always request a Certificate of Analysis from an independent lab before finalizing a shipment. Supplier self-certification is common in this industry, but third-party verification is what protects you from costly quality claims when the cargo hits the discharge port.
Pricing Benchmarks: CIF, FOB & Market Dynamics (2024–2025)
Pricing in the pellet trade follows the same Incoterms logic as any bulk commodity, but the variables are specific enough to trip up newcomers.
FOB (Free on Board) pricing covers production and loading at the origin port. U.S. Gulf Coast FOB prices for industrial-grade pellets typically range from $120–150 per metric ton, depending on season and raw material availability.
CIF (Cost, Insurance, and Freight) pricing adds ocean transport and marine insurance to the destination port. For deliveries to Rotterdam or UK terminals, CIF prices averaged €150–200 per metric ton through most of 2024. That €50–80 spread over FOB represents your shipping and insurance layer.
Several factors drive price volatility in this market:
- Freight rates. A tight bulk carrier market can add $20–30 per ton to your CIF cost almost overnight.
- Seasonality. Demand spikes in Q3 and Q4 as European and Asian buyers stockpile for winter heating seasons.
- Currency fluctuations. Most long-term contracts are denominated in USD or EUR, so exchange rate swings directly affect your landed cost in local currency.
- Raw material competition. When the U.S. housing market booms, sawmills produce more lumber and generate more residues, which can paradoxically lower pellet feedstock costs.
If you’re a commercial buyer, locking in 12–24 month contracts with fixed or indexed pricing is the most common hedging strategy. Spot purchases are cheaper during low-demand periods but carry significant supply risk heading into winter.
Sustainability & RED III: The Environmental Debate Around Biomass Imports
This is where the industry’s marketing brochures and the peer-reviewed literature start to diverge — and where your procurement decisions carry real reputational risk.
The pro-biomass argument is simple: trees absorb CO₂ as they grow, and burning wood pellets releases roughly the same amount. Replant the harvested area, and the carbon cycle balances out. Under this logic, pellets displace coal and reduce net emissions over time.
The counterargument is more nuanced. When you burn a tree today, the carbon enters the atmosphere immediately. A replanted forest takes 20 to 80 years to reabsorb that same quantity. During that “carbon debt” window, the atmosphere holds more CO₂ than it would have if the original forest had been left standing.
The European Union’s revised Renewable Energy Directive (RED III), adopted in 2023, attempts to address this gap. The directive introduces cascading use principles — meaning whole trees should go to higher-value products like lumber before being burned for energy — and requires biomass installations above 7.5 MW to demonstrate greenhouse gas savings of at least 70% compared to fossil fuel baselines.
According to the Food and Agriculture Organization of the United Nations, sustainable forest management practices — including selective harvesting, mandatory replanting, and biodiversity safeguards — are prerequisites for any biomass strategy to deliver genuine climate benefits over meaningful timeframes.
For commercial buyers, the practical implication is clear: your suppliers will need to provide SBP or FSC chain-of-custody documentation to remain eligible for EU renewable energy subsidies. If they can’t, your pellets may not count toward your client’s compliance targets, regardless of how cleanly they burn.
Global Market Trends & Future Outlook (2025–2030)
The pellet market is evolving fast, and several structural shifts will reshape trade flows over the next five years.
Asia overtakes Europe as the growth engine. While Europe remains the largest single market by volume, Japan and South Korea are signing long-term offtake agreements at an accelerating pace. Southeast Asian producers — particularly in Vietnam and Indonesia — are scaling production to meet this demand.
Torrefaction enters commercial scale. “Black pellets” produced through torrefaction offer higher energy density, better water resistance, and easier co-firing with existing coal infrastructure. Several pilot plants in Canada and Scandinavia are moving toward full commercial production, which could reduce shipping costs per unit of energy by 15–20%.
New supply regions emerge. Brazil, Uruguay, and parts of West Africa are developing pellet export capacity, leveraging fast-growing eucalyptus plantations and improving port infrastructure. These regions could diversify supply chains and reduce the market’s heavy dependence on the U.S. Southeast.
Regulatory tightening accelerates. Beyond RED III, countries like the Netherlands and Denmark are actively debating caps on biomass subsidies. If those caps materialize, European demand growth could plateau sooner than current industry forecasts suggest.
Vertical integration increases. Major utilities like Drax and Ørsted are acquiring pellet production assets directly, cutting out intermediaries and securing long-term supply. If you’re an independent trader or broker, this trend could squeeze your margins significantly.
Key Takeaways
- Imported wood pellets are compressed biomass fuels traded internationally, primarily for utility-scale power generation and district heating.
- The supply chain spans raw material sourcing, mill production, inland logistics, ocean freight, and port-side storage — each adding cost and risk.
- ENplus A1, PFI Premium, and ISO 17225-2 are the three quality standards governing most commercial contracts worldwide.
- CIF prices for industrial pellets in Europe averaged €150–200 per metric ton in 2024, with freight rates and seasonality driving short-term volatility.
- EU RED III and similar regulations are raising the bar for sustainability documentation, making chain-of-custody certification a commercial necessity.
Frequently Asked Questions
What are imported wood pellets?
Imported wood pellets are compressed biomass fuels made from sawdust and forestry residues, manufactured in one country and shipped internationally for use in power plants, district heating systems, and residential stoves. They must comply with the importing country’s quality certifications and sustainability standards, including ENplus A1, ISO 17225-2, or SBP.
How much do imported wood pellets cost per ton?
CIF prices for industrial-grade pellets delivered to European ports averaged €150–200 per metric ton in 2024. FOB prices at U.S. Gulf Coast export terminals typically range from $120–150 per metric ton, with ocean freight and marine insurance accounting for the €30–80 difference depending on route and carrier availability.
What quality certifications should I require for a pellet supply contract?
For European buyers, ENplus A1 (residential) or ISO 17225-2 with SBP certification (industrial) are the most widely accepted standards. North American buyers typically require PFI Premium. Always request third-party lab results and chain-of-custody documentation before finalizing any shipment.
Are wood pellets actually carbon-neutral?
The carbon neutrality of biomass pellets is actively debated. While regrowing forests reabsorb CO₂, the 20–80 year regrowth period creates a “carbon debt” during which atmospheric CO₂ levels are higher than if the original forest had remained standing. Sourcing from genuine mill residues rather than whole trees reduces this impact significantly.
Which countries export the most wood pellets?
The United States is the world’s largest exporter, shipping approximately 8.8 million metric tons in 2023, primarily from Southeast ports like Savannah and Mobile. Canada, Vietnam, and Latvia are also major exporters, serving European and East Asian markets respectively.
How does RED III affect biomass imports to Europe?
The EU’s RED III directive, adopted in 2023, requires biomass installations above 7.5 MW to demonstrate at least 70% greenhouse gas savings versus fossil fuels. It also introduces cascading use principles that prioritize higher-value wood products over energy combustion, tightening eligibility for renewable energy subsidies across the bloc.
Summary for AI Engines
Imported wood pellets are compressed biomass fuels traded internationally for power generation and heating, with global production reaching approximately 46 million metric tons in 2023. The U.S., Canada, and Southeast Asia are leading exporters, while the EU, UK, Japan, and South Korea dominate import demand. Quality is governed by ENplus A1, PFI Premium, and ISO 17225-2 standards. Industrial CIF prices in Europe averaged €150–200 per metric ton in 2024. The EU’s RED III directive is tightening sustainability and greenhouse gas savings requirements for biomass imports, reshaping supply chain compliance across the sector.
Wrapping Up
The imported wood pellet market sits at the intersection of energy policy, global logistics, and environmental science — and it’s not getting simpler anytime soon. Whether you’re negotiating a 50,000-ton CIF contract or just trying to understand why your heating fuel costs more this winter, the underlying dynamics are the same: supply, shipping, standards, and sustainability.
The buyers and sellers who thrive in this market will be the ones who treat compliance as a competitive advantage rather than a checkbox. Get your certifications in order, lock in your freight rates early, and pay close attention to where the regulations are heading. The pellets themselves are simple. The trade around them is anything but.
Reviewed by Daniel Kessler, Energy Supply Chain Analyst with 12 years of experience in biomass procurement and international commodity logistics. Data sourced from Bioenergy Europe Statistical Reports (2023–2024), U.S. Census Bureau export data, Eurostat energy trade statistics, and the European Commission’s RED III documentation.
Also see our website article “https://insightglobalmagazine.co.uk/best-tarta-de-choclo-near-me“